
Showing posts with label money. Show all posts
Showing posts with label money. Show all posts
Thursday, May 2, 2013
make every second count
Make every second count. Do the things you love, keep learning, and make your money work for you. Fun fact: it takes about 993,600 seconds to count 1 million dollar bills - that is about eleven and a half days. Go Team! Brett Ellen, The Kids Finance Coach.

Saturday, April 13, 2013
You would do WHAT?
Kids love to ask questions. And so do parents. Here are five questions that will give you great insight into what your kids are thinking and curious about. Take their responses a bit futher by asking them to describe ways of how they could save, invest, donate or spend money to do the things they want.
1. If you had a million dollars in your pocket, what would you do with it and why?
2. If you were to do something nice for someone, who would it be for and what would you do?
3. What kind of job do you think would be fun to have and why?
4. What is your favorite thing to do and why?
5. If you could buy something for someone else, what would you buy? Who would it be for and why?
Be sure to scroll down and over to the right to watch Kids Finance Coach Kids Keanu and Tristen's videos about how to save, invest, donate, spend money. Go Team! Brett Ellen, The Kids Finance Coach
1. If you had a million dollars in your pocket, what would you do with it and why?
2. If you were to do something nice for someone, who would it be for and what would you do?
3. What kind of job do you think would be fun to have and why?
4. What is your favorite thing to do and why?
5. If you could buy something for someone else, what would you buy? Who would it be for and why?
Be sure to scroll down and over to the right to watch Kids Finance Coach Kids Keanu and Tristen's videos about how to save, invest, donate, spend money. Go Team! Brett Ellen, The Kids Finance Coach
Thursday, April 11, 2013
Words with Money
I've got a great glossary of terms for you to check out: http://www.afn-net.com/glossary.cfm. Get to know the terms and you'll be a money word pro in no time. Go Team! Brett Ellen, The Kids Finance Coach
Tuesday, November 23, 2010
What Would You Do?

This holiday, think about what is most important in your life and be thankful.
Happy Thanksgiving!
Thursday, August 12, 2010
What About Scholarships?

There are numerous Web sites with information about scholarships and financial aid. For example, fastweb.com and finaid.org contain information about thousands of scholarships. In addition, fafsa.ed.gov provides an overview of federal student aid programs, including Pell Grants, campus-based aid programs, Stafford Loans, PLUS Loans, and others. Also, scholarshipexperts.com offers a free scholarship search targeted to the student's profile. Don’t forget, your local library and high school guidance office may have information about state-sponsored aid programs and scholarships sponsored by local organizations.
Parents: Financial aid can be a valuable source of funds to help finance your child’s college education. Don’t assume you won’t qualify. Read “What About Financial Aid for College?” to learn more.
Thursday, July 15, 2010
I’m Just a Kid! How Can I Save For College?
Adults have been told that they should have begun saving for college costs as soon as you were born! Well, I suggest it’s never too early for a kid to start saving money for his college expenses either. Here are some things you can do:
- Start earning your own money with a part-time or summer job. (Look at my old posts for ideas about how kids can earn money.)
- I’ve talked about how you can divide your money into categories to Save, Spend, Invest and Donate. Set aside a portion of the money you save for college expenses.
- Ask your parents for help opening a college savings account. You might even ask them to consider making a matching contribution each time you deposit your own money from work or gifts.
- When asked for gift ideas, suggest money for your college savings account.
Parents: Evaluate the potential benefits of contributing to tax-advantaged college savings vehicles, such as a 529 plan or a Coverdell Education Savings Account. Read “529 Lesson Plan: High Scores for 529 College Savings Program” to learn more.
Wednesday, May 26, 2010
Kids Finance Coach Donates $1,000 to School During Financial Literacy Month
I recently gave a presentation to about 900 high school students at Oaks Christian School. We talked about the basics of money management; including budgeting, responsible spending, charitable giving and investing. The energizing presentation was complete with music, a T-shirt launcher and prize wheel! The students were tremendously engaged and informed, which made for a really exciting time. (Click here if you want to find out how to bring The Kids Finance Coach to your school or group!)
 While at the presentation, my team and I awarded a $1,000 check to the non-profit school. According to the school's headmaster, the donation was the first time the school had actually received a donation from one of its speakers. But for those of you who have been following my blog regularly, you know who committed I am to charitable giving as one of the four building blocks of money management: save - spend - donate - invest. What better way to teach those students about giving back, than by showing them how it's done?
How have you been giving back, lately?

How have you been giving back, lately?
Tuesday, April 20, 2010
Pay Attention, Parents. This One’s for You!
Who are our children’s first teachers? That’s right…parents. April is Financial Literacy Month, so I’m doing what I can to help kids understand and become comfortable with financial concepts. Here’s a list of things YOU can be doing to help teach the valuable skill of money management to your child.
Ten Tips for Teaching Kids about Money
Ten Tips for Teaching Kids about Money
- It’s never too early to start talking about money with your kids.
- Don’t make personal finance topics taboo from kids. Talking about money is a learning opportunity. Any discussion is better than silence.
- Consider giving your kids an allowance. Set expectations about spending, saving and giving to charity.
- Encourage your kids to make their own money. That way, they connect work to money. Money is a means to an end, not an end in itself.
- Teach your child to ask, “how can I earn that?”
- Make sure saving is a habit. Reinforce it. Don’t forget to do it yourself.
- Don’t say “we can’t afford it”, say “we don’t need that right now.”
- Keep talking about issues like debt and credit with teenagers, even if they act like they are not listening. Credit/debit cards can feel like plastic funny money.
- Kids remember and copy parents’ behavior. So model good stewardship of money no matter how much you have. Discuss the basics of budgeting.
- Think of a financial planner as a resource. Just ask. They can help you talk with your kids about money.
Tuesday, February 23, 2010
Six Simple Steps to a Savings Plan
Build from the ground up with solid foundation!
• STEP SIX - Review Your Progress
Are you on track to reach your goals? How long will it take? Do you need to make any adjustments?
• STEP FIVE - Identify Your Earnings Plan
Will you be getting an allowance? Would you like to get a job? What other income can you expect?
• STEP FOUR - Establish a Savings Vehicle
Do you want to save your money at home? Do you want to open a bank account? Do you want to start a collection?
• STEP THREE - Set Up a Budget
How will you earn money? How much money will you need to reach your goals? How will you divide your money if you are saving for 2 budget items?
• STEP TWO: Set Your Goals
What are your financial goals? What do you WANT and what do you really NEED? What do you need now and what can wait a few months or even a year?
• STEP ONE: Get Educated
Where does money come from? How does a bank earn money? How can you make your money grow in value? What is compound Interest? (Hint: Check this blog’s archives. I’ve answered these questions before.)
• STEP SIX - Review Your Progress
Are you on track to reach your goals? How long will it take? Do you need to make any adjustments?
• STEP FIVE - Identify Your Earnings Plan
Will you be getting an allowance? Would you like to get a job? What other income can you expect?
• STEP FOUR - Establish a Savings Vehicle
Do you want to save your money at home? Do you want to open a bank account? Do you want to start a collection?
• STEP THREE - Set Up a Budget
How will you earn money? How much money will you need to reach your goals? How will you divide your money if you are saving for 2 budget items?
• STEP TWO: Set Your Goals
What are your financial goals? What do you WANT and what do you really NEED? What do you need now and what can wait a few months or even a year?
• STEP ONE: Get Educated
Where does money come from? How does a bank earn money? How can you make your money grow in value? What is compound Interest? (Hint: Check this blog’s archives. I’ve answered these questions before.)
Tuesday, September 22, 2009

Wow! What a Work- shop!
Last month I held my first Kids Finance Coach Workshop at my home and it was a blast! We invited kids and their parents to my house for an afternoon of fun activities to learn about money. We talked about things like allowance and spending, and even why and how to start saving money. Of course we couldn’t talk about money without learning about charitable giving. Money really can be used to help improve the lives of others.
Last month I held my first Kids Finance Coach Workshop at my home and it was a blast! We invited kids and their parents to my house for an afternoon of fun activities to learn about money. We talked about things like allowance and spending, and even why and how to start saving money. Of course we couldn’t talk about money without learning about charitable giving. Money really can be used to help improve the lives of others.
Parents, interested in having Coach Brett visit your community or starting a League of your own? Contact Denise Villanueva.
Thursday, June 25, 2009
Need Cash? Get to Work!
It's not always easy for kids to find a job. But here are some things kids can do to earn a little extra cash over the summer.
- Babysitting of course. Check your local hospitals to see if they offer a babysitting class, or learn more about babysitting and earn a babysitting certificate
Walk dogs/care for pets. Lots of people are too busy over summer to take care of their pets. Start your own pet care, dog walking business. Those long-haired dogs might need brushing, too.
Thursday, June 11, 2009
Learning the “Real” Value of Money through Giving
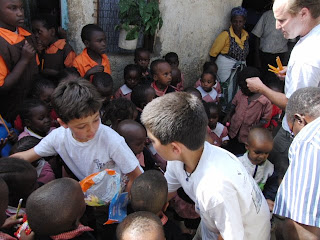
I have always believed that a necessary part of learning about money is learning how to value what you have and sharing with people who do not have as much as you. In an effort to teach these lessons to my own children, my wife and I helped our sons Keanu and Tristen establish their own non-profit organization call Turn Kindness On (TKO) Helping Hands. TKO Helping Hands motivates children of all ages to change their world through volunteering, harnessing their uniquely empathetic energy and empowering them to build a lifelong relationship with community service.
During a recent family vacation to Africa, our family did what we always do when we travel. We took money and supplies collected through the efforts of TKO and local students and delivered them to children’s organizations in the communities where we visited.
During a recent family vacation to Africa, our family did what we always do when we travel. We took money and supplies collected through the efforts of TKO and local students and delivered them to children’s organizations in the communities where we visited.

Click here to watch and see what a difference you can make when you understand the “real” value of money.
Monday, May 18, 2009

How Much Do Stocks Cost?
 When you think about buying stock, you should remember that there is risk that goes along with it, but there is also opportunity. So if someone asks the question “what are the best companies to invest in,” the answer must take into consideration the amount of risk that investor is willing to take. If the investor says, I don’t want to lose this money to make a fortune, but I really think it’s a great company - there are lots of companies that look promising. Many of them you’ve never heard of, but they believe they’ve got the next newest idea.
Have you ever heard the expression “Time heals all wounds”? When you get older, you’ll have typical grown-up experiences – like with boyfriends and girlfriends. You’ll break up and think the world is coming to an end. But over time, you’ll get over it and your life will get back to normal and things will be OK. Well it’s similar with stocks. If you invest in enough stocks and diversify – buying some companies that are less risky and some with medium risk and some that are real risky – over time it should all be ok. However it's important to remember that diversification doesn't guarantee you will make money and it is still possible to lose money in your investments.
 When you think about buying stock, you should remember that there is risk that goes along with it, but there is also opportunity. So if someone asks the question “what are the best companies to invest in,” the answer must take into consideration the amount of risk that investor is willing to take. If the investor says, I don’t want to lose this money to make a fortune, but I really think it’s a great company - there are lots of companies that look promising. Many of them you’ve never heard of, but they believe they’ve got the next newest idea.
Have you ever heard the expression “Time heals all wounds”? When you get older, you’ll have typical grown-up experiences – like with boyfriends and girlfriends. You’ll break up and think the world is coming to an end. But over time, you’ll get over it and your life will get back to normal and things will be OK. Well it’s similar with stocks. If you invest in enough stocks and diversify – buying some companies that are less risky and some with medium risk and some that are real risky – over time it should all be ok. However it's important to remember that diversification doesn't guarantee you will make money and it is still possible to lose money in your investments.
Monday, March 23, 2009

What’s the Difference between Stocks and Bonds?
 Stocks are ownership. When you own stock, you own part of a company. Bonds are “loanership”. You’re loaning money to a business or the government. In other words, a bond is debt.
So, when you buy a bond, you are lending money to a company. When you own a share of stock, you own a part of a company.
Let’s say you own a share of stock in a company that operates an amusement park. The company sells stock because they want to grow the company and they need to get capital, which is the money they can use to invest in growing the company. Now, if you own some of that stock, you own part of the company.
 Stocks are ownership. When you own stock, you own part of a company. Bonds are “loanership”. You’re loaning money to a business or the government. In other words, a bond is debt.
So, when you buy a bond, you are lending money to a company. When you own a share of stock, you own a part of a company.
Let’s say you own a share of stock in a company that operates an amusement park. The company sells stock because they want to grow the company and they need to get capital, which is the money they can use to invest in growing the company. Now, if you own some of that stock, you own part of the company.
Monday, February 23, 2009


 When a business needs money, they can get it one of two ways. They can sell p
 art of it – or they can borrow. Whey they sell stock, they sell part of the company. But a company may not want to give away ownership of all of the company. They may prefer for you to invest in their company as a bondholder. A bond is a promise to pay off the loan. So if they need money, they may want to borrow it – so they sell bonds – and promise to pay back the loan.
Now, let’s say the company does really well, and the value of the company increases. Does the value of your bond increase? No – because it’s just a promise to repay the loan. But if you own stock in a company, and the value of the company goes up, then your stock is worth more.
Friday, January 16, 2009


What is Compound Interest?
 There are two kinds of interest – simple interest and compound interest. You probably know how simple interest works.
 There are two kinds of interest – simple interest and compound interest. You probably know how simple interest works.
For example: If I have $10,000 and I earn 6% interest, how much money do I earn after one year?
Answer: $600
If I earned 6% every year for 12 years how much money would I have earned in interest?
Answer: $600 per year x 12 years = $7200. So adding that to my initial investment, I’d have a total of $17,200
Compounding Interest
If I have $10,000 and I earn 6% compounding interest, how much money do I earn in interest?
Answer: $600
If I earned 6% every year for 12 years how much money would I have earned in interest?
Answer: $600 per year x 12 years = $7200. So adding that to my initial investment, I’d have a total of $17,200
Compounding Interest
If I have $10,000 and I earn 6% compounding interest, how much money do I earn in interest?
Answer: Well, if I apply the “Rule of 72” (which we discussed in our last post) 72 divided by 6 (the rate of interest) = 12. That means my total money will double in 12 years to $20,000.
So why is the total amount of money higher with compounding interest than with simple interest ($20,000 compared with $17,200) if they both receive 6% interest?
Answer: With simple interest I earn the same amount of interest each year on the original $10,000. So every year I only receive $600. With compounding interest, I add $600 (interest) to my original $10,000. Then the next year I earn 6% on $10,600 which is $636. When added together I have $11,236. The following year I earn 6% on that amount
End of year 1 - $600 + $10,000 = $10,600
End of year 2 – 6% x $10,600 = $636. $636 + $10,600 = $11,236
End of year 3 – 6% x $11,236 - $674.16. $647.16 + $11,236 = $11,883.16
End of year 4 – 6% x $11,883.16 - $712.99. $712.99 + $11,883.16 = $12,596.15
End of year 5 – 6% x $12.596.15 - $755.77. $744.77 + $12.596.15 = $13,391.92
Do you see how this is calculated? Dan you continue to do the math?
So why is the total amount of money higher with compounding interest than with simple interest ($20,000 compared with $17,200) if they both receive 6% interest?
Answer: With simple interest I earn the same amount of interest each year on the original $10,000. So every year I only receive $600. With compounding interest, I add $600 (interest) to my original $10,000. Then the next year I earn 6% on $10,600 which is $636. When added together I have $11,236. The following year I earn 6% on that amount
End of year 1 - $600 + $10,000 = $10,600
End of year 2 – 6% x $10,600 = $636. $636 + $10,600 = $11,236
End of year 3 – 6% x $11,236 - $674.16. $647.16 + $11,236 = $11,883.16
End of year 4 – 6% x $11,883.16 - $712.99. $712.99 + $11,883.16 = $12,596.15
End of year 5 – 6% x $12.596.15 - $755.77. $744.77 + $12.596.15 = $13,391.92
Do you see how this is calculated? Dan you continue to do the math?
Tuesday, December 23, 2008
 The Rule of 72 is Cool!
When people invest money, they do it so they can make money. That’s called "getting a return on your investment.” Sometimes they want to know how long it will take to double their investment. To do this, we use the Rule of 72.
Take 72 and divide it by the amount of return on your investment. That is the number of years it will take to double your original investment.
For example: Ten year-old Keanu buys a bond for $10,000 and earns 6%. 72 divided by 6 = 12. So every 12 years, Keanu’s money doubles. When he is 22, he will have $20,000.
What if Keanu leaves that money alone until he retires at 60 years old? His money will double 4 times by then and he will have $160,000.
Let’s say Keanu used that original $10,000 and bought a stock that earns 12% return (72 divided by 12 = 6) he will have $20,000 in 6 years when he is 16. If he leaves that money alone until he retires, it will double 8 times and he will have over $2.5 million when he is 60 years old.
The Rule of 72 is based on a principle called “compound interest” (return), which is sometimes called “The 8th Wonder of the World”! I’ll explain more about compound return in my next post.
Here’s something VERY important to remember. Just because things happened in the past, doesn’t guarantee they’ll happen in the future. So we use historical return rates as an example. It doesn’t mean that if you invest in the stock market today, that you will receive 12% return on your investment every year. Also, when investing in stocks it is possible to lose money, so that the value of the stock could be less than the original investment.
Wednesday, November 12, 2008

 How Do Banks Make Money?
 When my oldest son was 4 years old, he said to me, “Hey Daddy, we need some more money so let’s just to go to the bank and get some.”
You probably already know that’s not how it works. You have to put money in the bank before you can take money out.
Banks are businesses that hold money for people like you and your parents. When you give them money, that’s called a deposit. What do you think they do with it? They loan that money to other people. They pay you interest to be able to use your money. The people who borrow the money have to pay interest to the bank for lending them the money. The bank charges the people who borrow the money a higher rate of interest than they pay to you. The difference between what they make and what they pay you is income for the bank.
For example: When your parents bought their house, they went to a bank to borrow the money. Now the bank owns the title to your house and your parents make monthly payments to the bank in order to pay back the bank for the money they borrowed.
Where did the bank get the money to loan your parents? They got money from all the people who deposit their money in the bank. The bank tells these people, “If you let us use this money, we will loan it to other people who need it – and we will pay you for allowing us to do this.” Let’s say the bank pays them 2% interest. To the people who borrow the money, they say, “We will lend you money but you must pay us interest to use that money.” They charge these people 5%. The bank makes 3% on that money.
So if you borrow money from the bank, you must pay the bank back for the entire amount you borrowed, plus you also must pay an extra amount called interest.
Come back next week – and bring your friends. I’ll explain more about interest.
Subscribe to:
Posts (Atom)